
19
Investors are reassessing European government bonds after a sharp market selloff pushed borrowing costs higher and widened differences between countries viewed as fiscally vulnerable and those seen as safer.
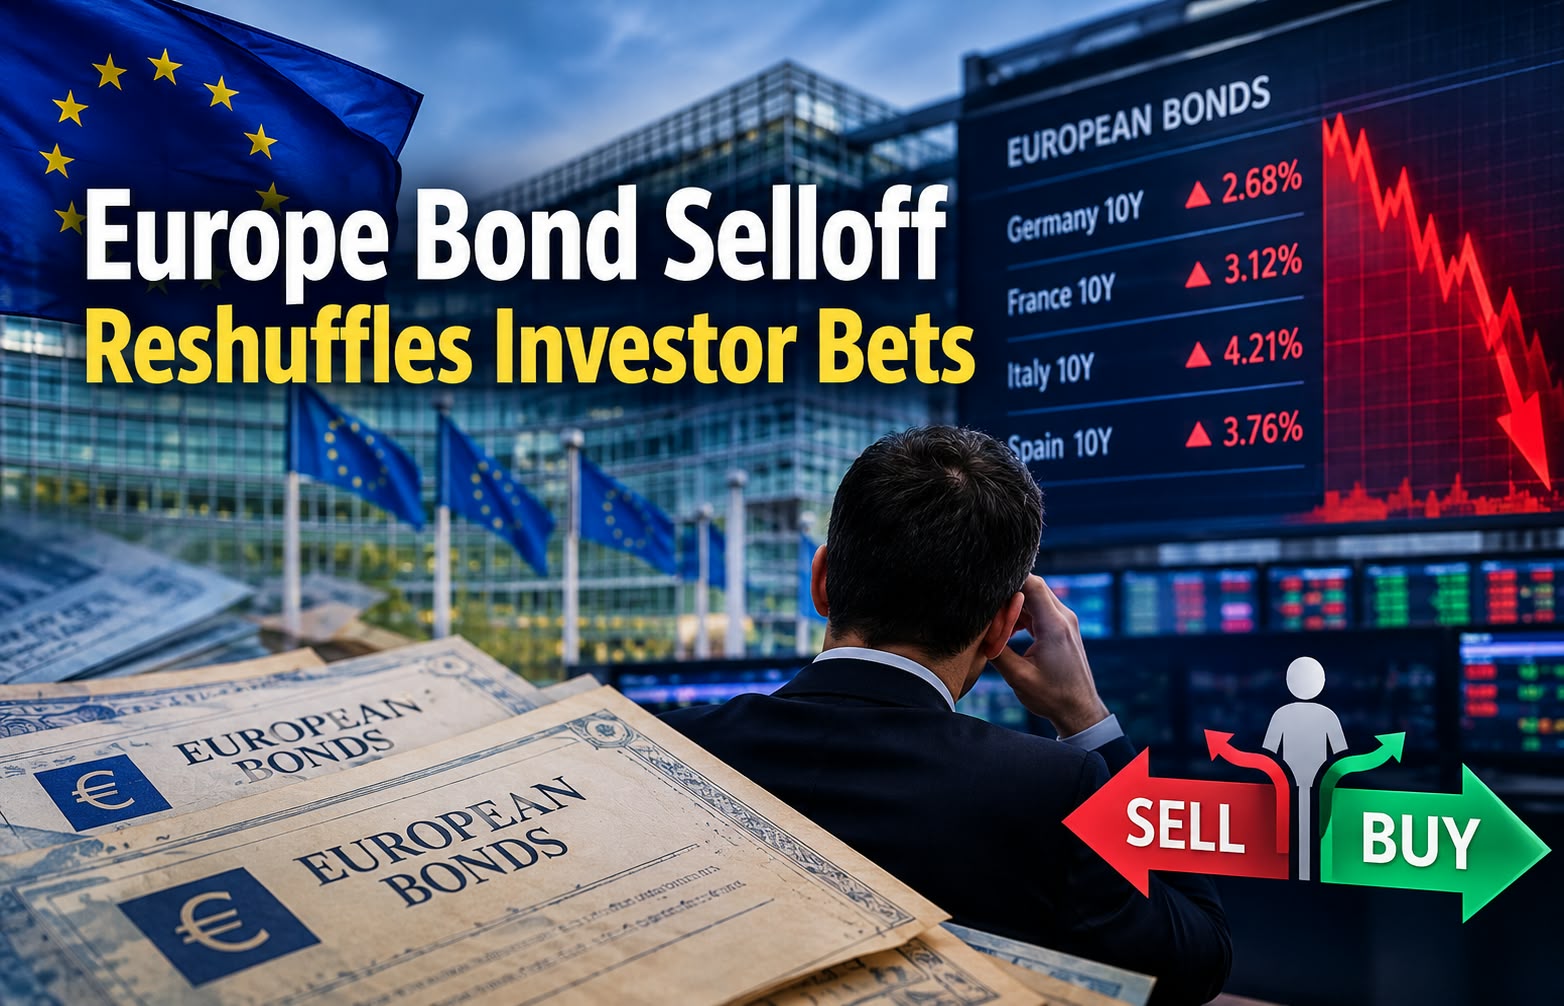
France has emerged as the main focus of investor concern, with scrutiny intensifying over its fiscal position and political outlook ahead of the 2027 presidential election. The yield on France’s 10-year government bond rose 70 basis points in September, reaching its highest level since 2002.
The shift has increased demand for German government bonds, traditionally viewed as a European safe-haven asset. Investors have also shown greater interest in debt from the Netherlands and Switzerland as they reassess sovereign risks across the region.
France’s fiscal position remains a key concern. The government expects its budget deficit to exceed its 5% target and plans to issue a record €340 billion ($381 billion) of bonds in 2027 to finance government spending and refinance existing debt, including borrowing accumulated during the COVID-19 period.
Other European bond markets have shown mixed performance. Italy and Britain remain exposed to higher borrowing costs but have so far avoided the level of pressure seen in France. Spain has attracted investor attention amid stronger economic performance and comparatively lower borrowing costs.
Investors are also watching whether concerns surrounding France spread to other European sovereign debt markets. A broader deterioration in market sentiment could push up yield spreads between countries with stronger and weaker fiscal positions.
The selloff has also weighed on European banks. Higher government bond yields can reduce the market value of banks’ sovereign debt holdings while increasing concerns over funding costs and exposure to weaker economic conditions. European bank shares fell sharply on October 7 as bond yields climbed and spreads widened.
The latest market moves highlight how quickly investor preferences can shift when concerns over public finances, interest rates, inflation and political uncertainty intensify. Higher borrowing costs could add further pressure to European governments already facing challenging fiscal conditions.
